Saudi Pipeline Shutdown Threatens 4% Hit to Global Oil Supply
A prolonged outage on Saudi Arabia’s East-West pipeline would expose how war, chokepoints and spare logistics capacity now shape oil markets.
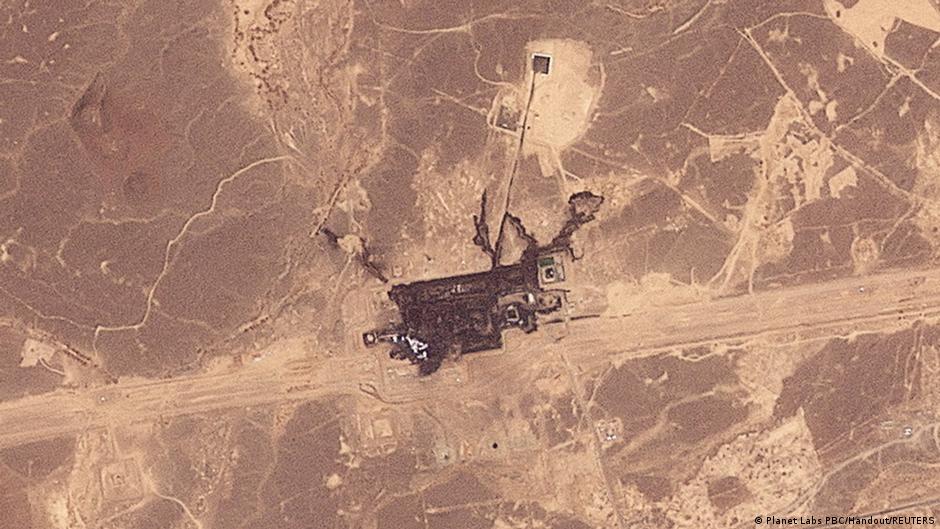
A prolonged halt on Saudi Arabia’s East-West oil pipeline could cut global oil supplies by 4 percent if Riyadh is unable to restore flows in the coming days, according to market sources cited by Reuters. The duration of repairs remains unknown after the pipeline was stopped following a Houthi drone attack, leaving one of the world’s most important oil-export routes under fresh scrutiny.
The immediate issue is operational: Saudi Arabia may soon face a shortage of crude available for export if the pipeline is not brought back online quickly. But the broader economic significance is larger. The incident shows how the geography of oil, once treated mainly as a question of reserves and production capacity, has become a question of routes, redundancy and political risk. In a market where millions of barrels per day can be redirected through a single corridor, the shutdown of that corridor becomes a global pricing event.
Saudi authorities have not provided full details on the scale of damage to the East-West pipeline or on the timeline for resuming crude pumping. The pipeline was suspended on September 11, with the Saudi energy ministry saying the decision was taken as a precautionary measure after drone strikes from Iraqi territory hit the provinces of Riyadh and Medina.
One Reuters source said repairs could take five to six weeks, while another said work might be completed sooner and that pumping could resume before repairs are fully finished.
The uncertainty matters because oil markets tend to price not only confirmed losses but also the probability of future disruption. A repair window measured in days would likely be absorbed differently from one measured in weeks. A shutdown stretching toward five or six weeks would raise questions about inventory drawdowns, alternative shipping capacity and the ability of buyers to replace Saudi barrels without bidding up prices elsewhere.
A Strategic Route Around Hormuz
The East-West pipeline stretches 1,200 kilometers across Saudi Arabia, connecting the kingdom’s main oil fields in the east with the port of Yanbu on the Red Sea. Its economic and strategic purpose is clear: it allows Riyadh to export millions of barrels of oil per day without relying on the Strait of Hormuz, where traffic has been restricted by Iran.
That bypass function has become more important since the start of Saudi Arabia’s war against Iran. Riyadh significantly increased its use of the pipeline after the war began. By June, crude exports through the route had reached nearly 8 million barrels per day, according to estimates from the International Energy Agency. In effect, the pipeline became a major release valve for Saudi exports at a time when the traditional Gulf route was constrained.
Historically, oil shocks have often been framed around production losses: embargoes, revolutions, wars or sanctions that remove barrels from the market. This episode highlights a related but distinct risk. The crude may exist underground, and production capacity may remain intact, yet the export system can still become the binding constraint. In that sense, logistics infrastructure has become part of the supply curve.
The pipeline’s importance also reflects a long-running structural feature of the global oil economy. Major consuming economies depend not only on producers but on the uninterrupted function of narrow maritime passages, ports, pipelines and storage hubs. The Strait of Hormuz has for decades been the most prominent example of such vulnerability. Saudi Arabia’s East-West route was designed to reduce exposure to that vulnerability, but the latest shutdown shows that alternative routes can themselves become targets.
Red Sea Risk and Market Consequences
The East-West corridor had already been under pressure before the September suspension. In recent weeks, the route’s effective capacity declined because of Houthi attacks on Saudi tankers in the Red Sea. In August, shipments through Yanbu stood at around 2.5 million barrels per day, the lowest level since 2013, according to the IEA’s latest monthly report.
That drop is important because it indicates that the problem is not limited to a single damaged pipeline segment. The export chain includes fields, pipelines, ports, tankers and maritime security. If tankers face higher risk in the Red Sea, a restored pipeline may not fully restore the previous export pattern. The bottleneck may simply move from land infrastructure to sea lanes.
For oil-importing economies, the consequences would depend on duration and substitution. A 4 percent decline in global supply would be large enough to affect benchmark prices, refinery margins and inflation expectations, particularly if traders believe the outage could persist. Higher crude prices can move quickly into fuel markets, raising transport costs and complicating central-bank calculations in economies already sensitive to energy-led inflation.
For producers, the disruption could create short-term price support, but it also increases the premium attached to geopolitical risk. That premium is economically ambiguous. It can raise revenues for exporters in the short run, yet it also encourages consuming countries to diversify suppliers, draw on inventories, accelerate efficiency measures or revisit strategic petroleum policies.
Saudi Arabia has experienced disruption on this route before. In April, the East-West pipeline was also attacked, but Saudi Aramco quickly returned it to service. The comparison will shape market expectations now. If the company again restores flows rapidly, the event may be treated as a contained interruption. If repairs take weeks, the episode could be read as evidence that attacks on energy infrastructure are becoming more effective and more economically consequential.
The central uncertainty remains the repair timeline. Saudi officials have not disclosed enough detail to allow the market to judge the damage independently. Until that changes, traders and policymakers will have to work with partial information: a suspended pipeline, reports of possible export shortages, estimates of a 4 percent global supply impact and conflicting views on whether repairs require days or weeks.
For Econpress readers, the lesson is structural rather than episodic. The oil market is not only a market for barrels. It is a market for secure routes, resilient infrastructure and credible spare capacity. The East-West pipeline was meant to protect Saudi exports from the risks of Hormuz. Its shutdown now demonstrates that in a fragmented security environment, even the bypasses require bypasses.